
Buying your first home in Ontario is exciting but it also comes with one of the biggest financial commitments you’ll ever make. Between down payments, closing costs, and the 13% HST on new homes in Ontario, the price can add up quickly.
That’s why the federal government’s proposed First-Time Home Buyers’ GST Rebate in Ontario could be a game changer. If passed into law, this rebate could refund up to $50,000 in GST on a newly built home. Combined with Ontario’s existing HST rebate, the savings for first-time buyers could be substantial.
Let’s break down exactly how it works without the legal jargon.
What Is the New First-Time Home Buyers’ GST Rebate in Ontario?
Currently part of Bill C-4, the proposed federal rebate would refund the 5% GST portion of HST on new homes purchased by first-time buyers.
Here’s how it’s structured:
- Full 5% GST rebate on new homes priced $1,000,000 or less
- Partial rebate for homes between $1,000,000 and $1,500,000
- No rebate for homes priced above $1,500,000
Example Scenarios
- $900,000 new home → Full $45,000 rebate
- $1,250,000 new home → 50% rebate ($25,000)
- $1,500,000 new home → No rebate
For Ontario buyers where housing prices often stretch into the millions, this rebate could make a significant difference in affordability.
How Does This Work With Ontario’s HST?
Ontario charges 13% HST on new homes:
- 5% GST (federal)
- 8% Ontario provincial portion
The new rebate only impacts the 5% GST portion, but Ontario already has its own New Housing Rebate that applies to the 8% provincial part worth up to $24,000.
Ontario Example:
- $1,000,000 new townhouse
- HST = $130,000 (5% GST = $50,000 + 8% provincial = $80,000)
- Federal GST rebate = $50,000
- Ontario provincial rebate = $24,000
- Final HST bill = $56,000 instead of $130,000
Who Qualifies for the First-Time Home Buyers’ Rebate in Ontario?
To be eligible, you must meet all the following criteria:
- At least 18 years old
- A Canadian citizen or permanent resident
- First-time buyer (you and your spouse/partner haven’t owned a home in the current year or past four years)
- The home must be your primary residence
- You or your spouse/partner haven’t claimed this rebate before
- Purchase must be made as an individual (no corporations or partnerships)
What Types of Homes Are Eligible?
The GST Rebate in Ontario applies to newly built homes only, not resales.
Eligible properties include:
- Detached houses
- Semi-detached homes and townhouses
- Condominiums
- Duplexes
- Modular and mobile homes
- Floating homes
- Co-op housing units (if new and taxed)
You can either purchase from a builder or build your own home and still qualify.
Timing Matters: Key Dates to Know
To qualify for the GST Rebate in Ontario, your agreement or construction must fall within these timelines:
- Buying from a builder? Agreement must be signed on or after May 27, 2025 and before 2031. Construction must start before 2031 and finish before 2036.
- Building your own home? Construction must begin on or after May 27, 2025, and be substantially complete before 2036.
You won’t qualify if:
- You take over someone else’s pre May 27, 2025 purchase agreement.
- You cancel and re-sign an old agreement to “reset” the date.
- You or your partner have already claimed the rebate.
Limitations
The proposed GST Rebate in Ontario also includes specific restrictions to prevent misuse:
- You cannot claim the FTHB GST rebate if you or your spouse/common-law partner have previously claimed it.
- If the home was purchased through an assignment sale, the original purchase agreement must not have been entered into before May 27, 2025.
- An anti-avoidance rule prevents cancelling a pre May 27, 2025 agreement and re-signing after that date to qualify.
These rules are designed to ensure the rebate only benefits genuine first-time buyers of newly built homes.
How Does This Work for Owner-Built Homes?
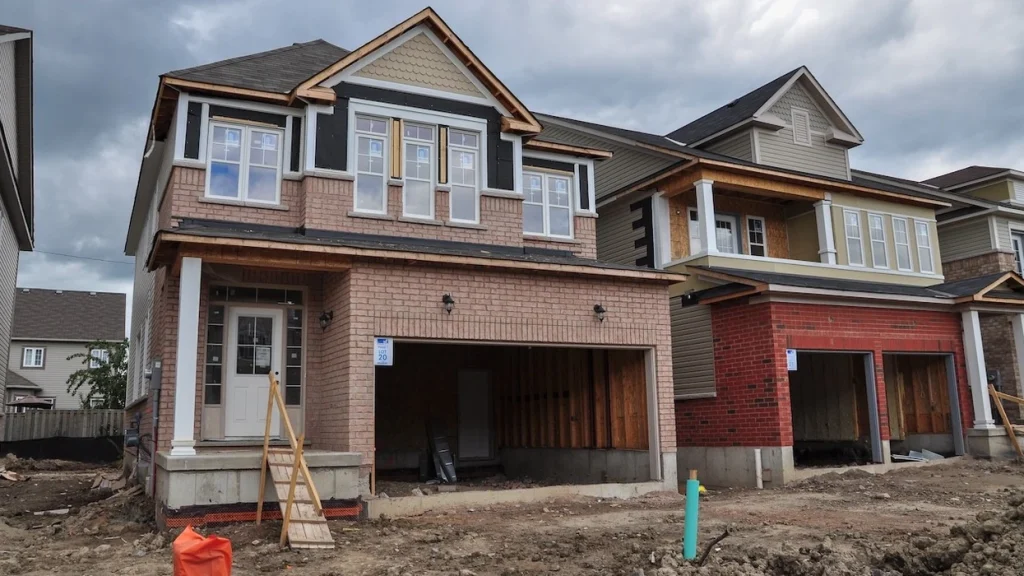
If you’re building your own home in Ontario, you may be eligible for the full $50,000 GST Rebate in Ontario.
But there’s a catch:
- You must keep all original invoices and receipts.
- The CRA requires detailed documentation for construction projects.
- Missing paperwork could result in a denied claim.
How to Claim the rebate
Once the rebate becomes law, the CRA will issue official guidance. It will likely follow the current New Housing Rebate process, which involves forms like:
- GST190 / GST191 (for owner-built homes)
- Builder credits (if purchasing from a builder, they may apply the rebate directly at closing)
Common Pitfalls to Avoid
Here are the top reasons buyers might miss out on the rebate:
- Purchasing a resale home (rebate only applies to new builds).
- Buying through a corporation or partnership (only individuals qualify).
- Already claiming the First-Time Home Buyers’ Rebate in the past.
- Agreements dated before May 27, 2025, even if later assigned to you.
Why This Matters for Ontario Home Buyers
Ontario’s real estate market is one of the most expensive in Canada. For first-time buyers in Toronto, Mississauga, Brampton, and Barrie, even modest new homes often come close to the $1M threshold.
This rebate could mean the difference between:
- Being priced out of a home purchase, or
- Finally being able to afford a new build.
By combining the federal and the GST rebate in Ontario, buyers could save up to $74,000 in taxes on a qualifying new home.
Final Thoughts: Don’t Count the Rebate Until It’s Law
While this rebate is exciting, it’s still just a proposal under Bill C-4. The CRA will not process applications until the law passes and receives Royal Assent.
If you’re planning to buy a new home in Ontario after May 2025, keep this rebate in mind, but don’t budget for it until it’s official. In the meantime, consult an accountant who specializes in real estate taxes to ensure you’re maximizing all available rebates and planning your purchase strategically.
Frequently Asked Questions
Is the First-Time Home Buyers’ GST Rebate in Ontario available now?
No. As of 2025, it’s still a proposed measure in Bill C-4 and not yet law.
Do I need an accountant to claim the rebate?
Not required, but recommended. An accountant can help ensure eligibility, manage documentation, and file correctly with CRA.